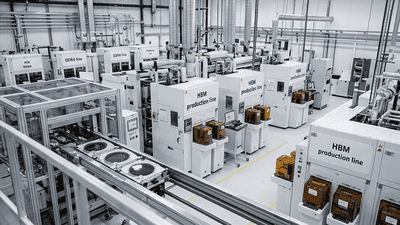
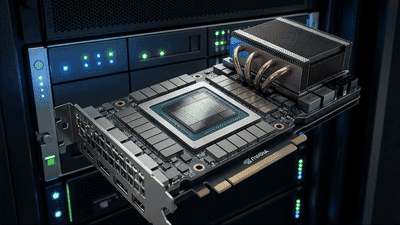
In modern high-performance computing and AI system design, High-Bandwidth Memory (HBM) and Chip-on-Wafer-on-Substrate (CoWoS) packaging have evolved from complementary technologies into a tightly coupled investment thesis. This post examines why investors, system architects, and policymakers should view HBM and CoWoS as an intertwined opportunity—how technological synergies, supply-chain economics, customer demand patterns, and geopolitical dynamics create a single strategic story rather than two separate bets.
What HBM and CoWoS are, and why they pair naturally
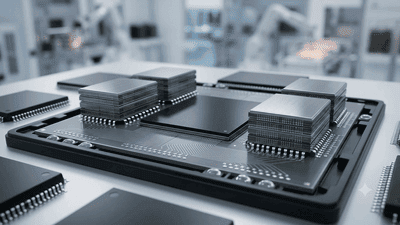
HBM is a stacked DRAM architecture optimized for extremely high bandwidth and energy efficiency per bit. CoWoS is an advanced 2.5D packaging solution that mounts chips (for example, GPUs or AI accelerators) next to or on top of silicon interposers and integrates HBM stacks through short, dense interconnects. The physical and electrical proximity that CoWoS provides is what lets HBM deliver orders-of-magnitude better effective bandwidth than traditional DDR or GDDR solutions.
The pairing is natural for several reasons:
- Electrical performance: CoWoS minimizes trace length and signal degradation between compute die and HBM stacks, preserving high-speed signaling and low latency.
- Thermal and mechanical integration: CoWoS supports optimized thermal paths and mechanical stability for high-stack-count HBM, enabling higher-power accelerators to function reliably.
- Form factor and density: CoWoS allows multiple HBM stacks around a single compute die in a compact footprint, crucial for datacenter accelerator density and edge-performance per watt.
Market drivers that make the bundle investable
Several macro and micro trends have elevated demand for HBM + CoWoS solutions, making the bundle attractive to investors and strategic buyers.
- AI and ML compute growth: Large models and transformer architectures place enormous pressure on memory bandwidth. HBM in CoWoS packaging is often the only pragmatic path to deliver required memory throughput within power and thermal budgets.
- HPC and scientific workloads: Simulations and data-intensive workloads favor high-bandwidth, low-latency memory close to compute, again pointing to HBM + CoWoS.
- Heterogeneous integration: Modern systems increasingly combine logic nodes, accelerators, and memory in multi-die packages. CoWoS is a proven platform for this transition, raising the implied addressable market for both packaging and memory vendors.
- Time-to-market pressure: OEMs prefer packaged solutions that minimize PCB complexity, validation cycles, and system redesign risk. CoWoS with pre-integrated HBM simplifies system-level integration.
Economics of bundling: capex, margins, and scale
At first glance, HBM and CoWoS appear capital-intensive—advanced DRAM fabs, TSV formation, hybrid bonding, silicon interposer production, and OSAT packaging lines require massive investment. But economics improve when you consider them together.
- Value capture: Integrated vendors or closely partnered ecosystems capture more value across the stack—wafer sales, interposer fabrication, assembly, testing, and module integration all contribute to margin. Bundling allows suppliers to monetize packaging premiums alongside memory ASPs.
- Unit economics: CoWoS packages are higher ASP items, and customers are willing to pay premiums for validated, high-performance modules that reduce system risk. This offsets some of the high fixed costs in packaging and yields-in-motion.
- Scale effects: As demand for AI accelerators grows, fixed packaging investments amortize across larger volumes. Vendor investments in CoWoS capacity therefore become more attractive as HBM demand scales.
- Customer lock-in: CoWoS + HBM combos reduce switching costs for OEMs, encouraging multi-year procurement contracts and capacity reservations—this creates revenue visibility that de-risks capex for suppliers.
Supply chain structure and concentration risks
The bundled thesis highlights concentrated nodes in the supply chain where investments matter most. Key chokepoints include:
- Advanced DRAM fabrication: Only a handful of vendors produce HBM-capable DRAM die at scale. Capacity decisions in these fabs directly control HBM availability.
- Silicon interposers and advanced substrates: High-quality interposer fabrication is specialized, with limited global capacity for large-area interposers used in CoWoS.
- OSATs with hybrid bonding and high-precision stacking: Not every OSAT can produce high-yield CoWoS assemblies; capacity expansion is costly and time-consuming.
- Test-and-validation infrastructure: Validating multi-die packages requires sophisticated testing equipment and expertise—this is another scarce resource that influences shipping timelines and yields.
These concentration points mean that investments which expand capacity or diversify geographic locations for these nodes have outsized strategic value. Investors should favor companies and regions that reduce single-point-of-failure risks while improving throughput for integrated HBM-CoWoS assemblies.
Technology risk and the path forward
Every investment thesis must account for technology risk. For HBM and CoWoS, the primary technical uncertainties are yield learning, thermal management, and alternative architectures.
- Yield learning curve: Both high-die-count HBM stacks and large-area interposers have complex yield dynamics. Early production often suffers from lower yields, which can depress margins until engineering improvements accumulate.
- Thermal limits: As HBM stack counts and compute die power rise, thermal dissipation becomes a bottleneck. Advances in package-level cooling, thermal interface materials, and liquid-cooling-compatible substrates will be decisive.
- Competition from other formats: Alternatives such as advanced GDDR iterations, on-chip memory advancements (e.g., chiplet-level SRAM innovations), or novel packaging like native 3D monolithic stacking could reduce the growth trajectory for HBM + CoWoS.
Nonetheless, current performance envelopes and ecosystem maturity give HBM + CoWoS a multi-year runway. Near-term, the deployment cadence of large AI training clusters and specialized HPC systems sustains demand while suppliers scale yields and packaging capacity.
Strategic positions: where to invest within the bundle
Investment opportunities exist across multiple layers of the stack. Each has a distinct risk-return profile:
- Memory manufacturers (HBM die producers): High capital intensity, direct exposure to DRAM cycle risk, but large upside if they maintain wafer leadership and pricing power.
- OSATs and packaging specialists: Lower wafer-cycle correlation, but critical to enabling CoWoS scale; investments here benefit from recurring assembly revenue and rising per-unit ASPs.
- Interposer and substrate suppliers: More specialized, with higher barriers to entry; success depends on process capability for large-area, fine-pitch interposers and relationships with major IDM/OSAT customers.
- System integrators and OEMs: Indirect exposure via demand for high-performance modules; some OEMs choose co-investment strategies with suppliers to secure prioritized allocations.
- Enabling equipment vendors: Suppliers of hybrid-bonding tools, thermal interface equipment, and high-precision die placement benefit from multi-year growth as packaging complexity rises.
Case study: how a cloud provider’s procurement strategy validates the bundle
Consider a hypothetical hyperscaler planning a fleet of AI training clusters. Their primary objectives are performance per watt, rack-level throughput, and predictable supply for scale-out. The procurement team examines two options:
- Option A: Build systems around discrete GPUs with GDDR and conventional PCB routing to memory. Lower per-unit cost initially, but poorer performance per watt and larger rack footprint.
- Option B: Purchase CoWoS-packaged accelerators with integrated HBM stacks. Higher upfront cost per module, but superior bandwidth, lower system-level power, and simplified integration.
The hyperscaler chooses Option B and negotiates long-term supply and co-investment in packaging capacity. This move reduces their unit cost over a multi-year horizon because improved efficiency allows denser racks and fewer servers for the same compute capacity. The supplier benefits from guaranteed volume, enabling capital expansion in both HBM wafer output and CoWoS assembly lines. This mutually reinforcing dynamic illustrates the bundled thesis in practice.
Valuation implications and financial signals to watch
For investors, certain metrics and announcements indicate the health of the bundled thesis:
- Long-term supply agreements and capacity prepayments from hyperscalers or large OEMs—these de-risk future revenue and support capex guidance.
- Packaging capacity expansion announcements, particularly for hybrid bonding and large-area interposers—these reveal where bottlenecks will ease.
- Yield improvement reports and gross-margin expansion tied to HBM/CoWoS products—sustained margin recovery signals durable economics.
- Backlog length and ASP stability for HBM and CoWoS packages—rising backlog with stable ASPs suggests supply tightness and pricing power.
Conversely, a sudden surge in wafer output without corresponding packaging capacity growth can indicate future margin pressure as finished-module supply remains constrained by OSAT availability.
Geopolitics and policy: where the thesis intersects national strategy
Governments increasingly view advanced packaging and high-performance memory as strategic technologies. Policy actions that matter include export controls, subsidies for domestic packaging capacity, and workforce development for semiconductor assembly.
- Incentives for domestic OSATs or interposer fabs reduce geopolitical risk for local buyers and create investment opportunities in beneficiary firms.
- Export controls on EUV or packaging tools can slow capacity expansion in certain regions, advantaging suppliers located in allied jurisdictions.
- Public-private partnerships that co-fund packaging facilities accelerate capacity buildout and often include procurement commitments that validate private investment.
Investors should monitor policy developments, as supportive measures can materially increase project IRRs for CoWoS and HBM initiatives, while restrictive policies can reroute demand and create short-term dislocations.
Risks to the bundled thesis
Every investment story carries risks. For the HBM + CoWoS bundle, primary concerns include:
- Technological displacement: Breakthroughs in monolithic 3D integration or radically different memory architectures could alter the current value proposition.
- Overcapacity in packaging: If many OSATs expand simultaneously and demand growth slows, ASP compression could follow, pressuring margins.
- Macro downturn in cloud capex: AI model training growth currently sustains demand; a prolonged slowdown in hyperscaler spending would reduce near-term capacity utilization.
- Execution risk: Yield or quality issues in high-volume CoWoS production can delay revenue and require costly remediation.
Mitigating these risks requires diversified exposure across the stack, active monitoring of technology trends, and favoring firms with strong customer relationships and demonstrated engineering excellence.
Practical recommendations for stakeholders
Based on the bundled thesis, here are targeted actions for different stakeholders:
- Investors: Favor companies showing long-term supply contracts, visible packaging capex plans, and improving HBM/CoWoS margins. Consider exposure to equipment vendors enabling hybrid bonding for diversified risk.
- Suppliers: Pursue vertical partnerships across memory and packaging, secure anchor customers with capacity reservations, and invest early in yield-improvement teams.
- OEMs and hyperscalers: Lock in multi-year supply where density or performance matters, co-invest in packaging lines if beneficial, and prioritize design modularity to accommodate multiple packaging flavors.
- Policymakers: Support domestic packaging ecosystems via incentives and workforce programs to reduce strategic vulnerabilities in critical compute supply chains.
Outlook: a multi-year structural story
HBM and CoWoS together form a structural investment thesis rooted in technical necessity and systems-level economics. While both technologies require heavy upfront capital and face short-term execution risk, their combined role in enabling next-generation AI, HPC, and dense datacenter compute gives them a multi-year runway.
Market signals in the near term—customer supply commitments, packaging capacity buildouts, and yield improvements—will determine the pace of commercialization and margin expansion. Over a longer horizon, innovation in cooling, interconnect, and integration methods will expand addressable markets and potentially lower costs, strengthening the bundled investment case.
Closing thoughts
Treat HBM and CoWoS not as two adjacent technologies but as a single, interdependent value chain. Investment decisions that recognize this coupling—allocating capital to memory vendors, packaging specialists, interposer makers, and enabling equipment providers—stand to benefit from synergies that arise when capacity constraints are relieved and customers commit at scale. The most compelling opportunities will be those that de-risk one or more chokepoints in the bundle: packaging yield, interposer capacity, and long-term customer agreements.